FREE CREDIT REPORTS
WEEKLY · THREE U.S. BUREAUS
Last checked: October 11, 2026. You do not need to buy a credit monitoring subscription just to review your U.S. credit reports. The three nationwide credit bureaus—Equifax, Experian and TransUnion—permanently allow consumers to request one free online credit report from each bureau every week through AnnualCreditReport.com. A free credit report, a credit score, a security freeze and a paid monitoring product are different things.
This independent guide explains the trusted request route, what to check, what an error dispute involves and how to avoid fake ‘free report’ trial subscriptions. We do not request credit card details, Social Security numbers or consumer reports.
Know the difference before paying
| Service | What it provides | Generally free? | Main caution |
|---|---|---|---|
| AnnualCreditReport.com reports | Your credit history from Equifax, Experian and TransUnion | Yes, up to weekly online under current nationwide-bureau program | Credit scores typically are not included |
| Credit score service | A numerical estimate derived from credit report data | Some versions free; others paid | Scores/models vary; do not confuse them with reports |
| Credit freeze | Limits access for most new-credit applications | Free from the three major bureaus | May need to temporarily lift when applying for credit |
| Paid monitoring / identity services | Alerts and other protections under a provider’s plan | Not necessarily | Check billing, auto-renewal and actual coverage |
1. Use the only authorized central report website
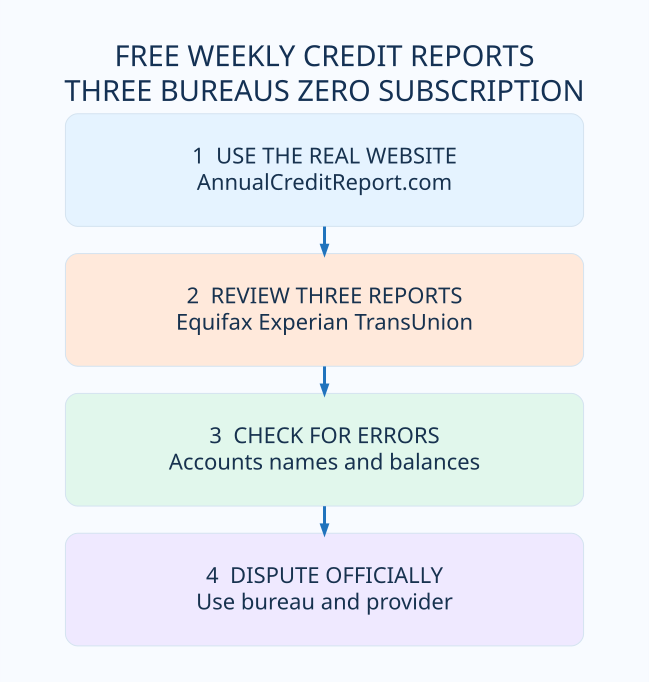
The Federal Trade Commission identifies AnnualCreditReport.com as the authorized centralized website for legally required free reports. It also publishes the phone number 1-877-322-8228 for requesting reports and a mail-request method. Typing the correct domain yourself avoids lookalike advertisements.
The FTC says the three national bureaus permanently extended weekly no-cost online reports. Read its permanent weekly reports announcement. “Annual” in the domain name does not mean you must wait twelve months between current free online requests.
2. What the application will ask for
The service or selected bureau may ask for your name, date of birth, address, Social Security information and security verification to confirm identity. It may use questions about prior accounts or two-factor authentication. Enter those details only into the verified bureau process, never an email form on a discount blog.
- Open AnnualCreditReport.com directly.
- Select which of the three national bureau reports you want.
- Complete the identity verification steps in the official flow.
- Review or securely save your copy after authentication.
- Keep copies private, since a report contains sensitive financial information.
3. Does looking up your own report affect your score?
Requesting your own report is a consumer inquiry, not a lender’s new-credit hard inquiry. The Consumer Financial Protection Bureau explains that these inquiries do not affect your credit score. This is different from applying for a new loan or card that results in a qualifying lender inquiry.
4. What should you check on each report?
| Review area | Example problem | Useful action |
|---|---|---|
| Personal information | An address or name that is not yours | Gather records and verify whether it is a reporting error |
| Credit accounts | An account you never opened | Consider identity theft; use IdentityTheft.gov |
| Payment history | Incorrectly reported late payments | Check statements and dispute with supporting proof |
| Balances and account status | An old closed account shown incorrectly | Compare against creditor records |
| Collections or duplicate records | An inaccurate debt entry | Check dates, owner and reporting rules before disputing |
A difference between bureaus does not automatically prove fraud, since companies report information at different times and may not report to every bureau. Focus on actual inaccuracies or suspicious entries.
5. How to dispute a genuine error
The CFPB’s September 2026 dispute guidance explains that correcting an error generally involves contacting both the bureau reporting it and the company that supplied the information. Describe the specific inaccurate information and provide copies of relevant evidence using the official dispute process. Keep your originals.
- Identify which credit report and entry contain the possible error.
- Gather statements, letters or other support without altering originals.
- Follow the credit bureau’s official dispute procedures and retain a confirmation.
- Where relevant, also contact the company that furnished the disputed information.
- Review the investigation result and updated report; further steps depend on your circumstances.
A credit repair advertisement promising to erase accurate negative information for a fee is not proof that your history will change. Your right to dispute inaccurate reporting is separate from purchasing credit repair services.
6. Fraud concerns and credit freezes
If you find an account you do not recognize, an unexplained inquiry or signs of impersonation, consider the official IdentityTheft.gov recovery guidance. A security freeze at each of the three nationwide bureaus is generally free and can make opening new accounts in your name harder, but you may need to lift a freeze for legitimate applications.
Monitoring and freezes do not eliminate every identity-theft risk. Keep credentials secure, turn on multifactor authentication where offered, and do not send your full credit report to a public website.
7. A 15-minute periodic report review
- Request reports through the correct central website.
- Check personal details for unknown addresses or names.
- Review open and closed accounts for accounts you do not recognize.
- Verify payment history and balances against known records.
- Record any legitimate issue and choose the bureau’s official dispute path.
- Store downloaded copies securely or remove them from shared devices.
- Repeat when needed without signing up for paid monitoring merely to get a free report.
Frequently asked questions
Are weekly reports guaranteed free? The FTC describes permanent free weekly online reports from each of the three nationwide bureaus through the authorized central site. Is a score included? Not necessarily; a score is separate. Will my own request lower my score? No, reviewing your own report is not a lender hard inquiry. Can a third-party savings blog order my report? You should not share identity information with one.
Related reader resources
For official state-held funds rather than credit information, read our unclaimed-property search guide. Avoid fake free-service paywalls with the Deal Reality Check.
Official sources
- FTC: Free Credit Reports
- FTC: Permanent Weekly Free Credit Reports
- CFPB: Disputing Inaccurate Credit Report Entries
- CFPB: Own-Report Inquiries and Score Effects
Financial information disclaimer: Happy Perks Calendar is not a credit bureau, financial advisor, credit repair company or identity verification service. This is general educational information, not personalized credit advice.
Share this guide
Know someone who could use these official-source checks? Share the link. Terms and availability may change.

